
EPS is useful precisely because it compresses a lot into one number. That compression is also what makes it dangerous when read without context.
- EPS is a useful result, but it is not a complete explanation.
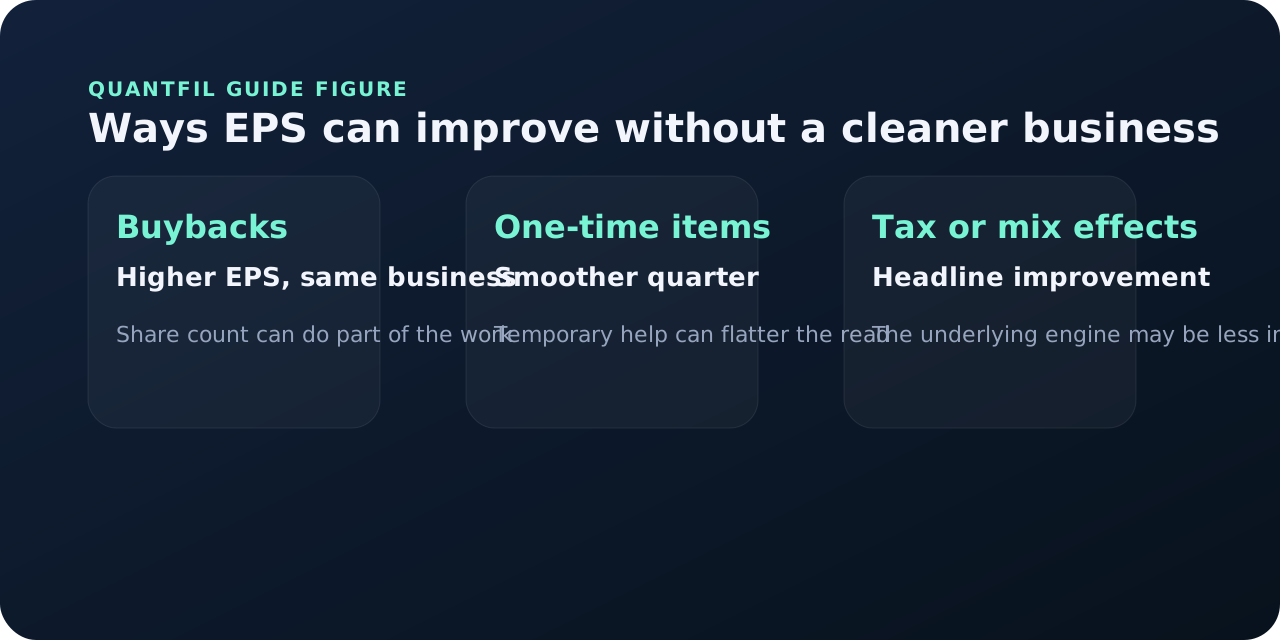
- Share count changes, margins, and one-time items can all reshape EPS.
- The best EPS habit is to ask whether cash flow and diluted share count support the same conclusion.
Why this matters
This matters because investors often use EPS as a shorthand for quality. That shortcut is sometimes fine, but it can break badly when the drivers are less durable than the headline suggests.
What to look for
Look at operating income, diluted share count, tax rate, non-GAAP adjustments, and cash flow. Those pieces often tell you whether the EPS move is broad-based or unusually narrow.
A practical workflow
Start with EPS, then deconstruct it into operations, share count, adjustments, and cash support before deciding how much it should matter to your thesis.
- Start with the reported EPS move.
- Check operating income and margins to see whether the core engine improved too.
- Review diluted share count, adjustments, and tax effects.
- Use cash flow to decide whether the quarter feels genuinely stronger.
Common mistakes
The common mistake is treating EPS as if it were a direct read on business improvement. It is really a final output that depends on several other moving parts.
Worked example / hypothetical, not company data
Separate profit growth from denominator change
Net income falls from 100 to 96 million while diluted weighted-average shares fall from 100 to 80 million. Assume a simple single-class structure.
Why does EPS rise despite lower income?
EPS rises from 1.00 to 1.20 because the denominator falls faster than profit. That is a 20% EPS increase alongside a 4% income decline. Investigate the repurchase cost, financing, and share issuance before describing the outcome as improved operations. A per-share benefit and an operating improvement are distinct claims.
Source check: Use the EPS note's weighted-average diluted count, not the closing share count on the cover page.
Ask yourself
- Would the quarter still feel strong if diluted share count had not helped?
- Which driver did most of the work: operations, accounting, or capital allocation?
- What part of the EPS story feels least repeatable?
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Try the next workflow
Frequently asked questions
Should investors ignore EPS?
No. EPS is useful. The mistake is treating it as complete rather than as a result that needs to be explained.
Can buybacks make EPS look better?
Yes. Buybacks can help EPS even when the underlying business changed less than the headline suggests.
What is the best companion metric to EPS?
Operating cash flow is often the quickest check because it tests whether the quarter generated real cash support.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.