
A filing is easier to trust when the cash behavior looks healthy too. The cash flow statement can tell you whether the business is converting reported performance into real financial flexibility.
- Cash flow helps you test whether earnings quality is improving.
- Working capital and capex can change the quality of the quarter even when EPS rises.
- A stronger filing usually shows consistency across earnings and cash generation.
Why this matters
Earnings quality matters because the market often prices the headline before it checks the durability of that headline. Strong operating cash flow and sensible capex usually make a reported improvement more believable.
What to look for
Start with operating cash flow, then look at capital expenditures, working-capital movement, and free cash flow. If those pieces deteriorate while earnings improve, the filing may be telling a more cautious story than the income statement alone.
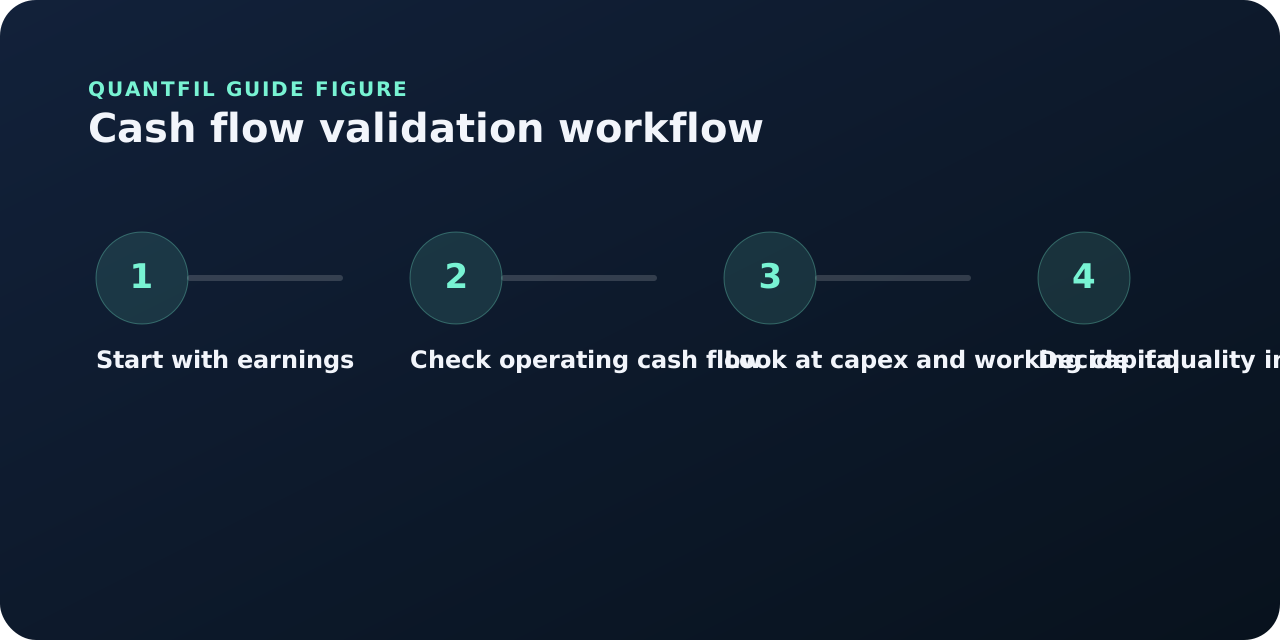
A practical workflow
Use cash flow as a validation layer. It does not need to be perfect every quarter, but over time it should help confirm whether the reported earnings profile is strengthening or weakening.
- Start with the reported earnings story.
- Read operating cash flow next.
- Check capex and working-capital movement.
- Decide whether cash behavior supports the narrative.
Common mistakes
The common mistake is treating cash flow as a secondary check instead of a central one. Another is looking only at one quarter without considering working-capital timing or capex requirements.
Worked example / hypothetical, not company data
Remove a timing benefit before celebrating conversion
Annual net income is 60 million and operating cash is 90 million. An increase in payables contributed 35 million to operating cash.
Does 150% cash conversion settle earnings quality?
The reported ratio is 90 divided by 60, or 1.5 times. Excluding that single timing contribution gives a sensitivity of 55 million, not a replacement GAAP cash-flow figure. Determine why payables increased and whether payments are merely deferred. Strong conversion can coexist with a funding benefit that will not repeat.
Source check: Label the 55 million as an illustrative sensitivity and inspect supplier terms before assuming a reversal.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Why not just rely on EPS?
EPS is useful, but it does not tell you whether the business is converting that performance into cash.
Does weak cash flow always mean poor quality?
Not always, but it does mean the filing deserves more context and skepticism.
What if capex is high because the company is investing?
That can be healthy, but the filing should make clear why the investment is likely to pay off.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.