
Many readers open a filing and immediately drop into the statements. That can work, but it is usually better to start by understanding what document you are holding and what period it is trying to explain.
- Start by identifying the form and period.
- Use the first read to find the main change, not every detail.
- The best next step is usually one proof section, not the entire document.
Why this matters
The first few checks matter because they frame the rest of the read. If you miss the form type, the reporting period, or the main issue in the filing, the rest of the details become much harder to place correctly.
What to look for
Start with the form, the filing date, the report period, the summary of what changed, and the one or two sections most likely to prove or challenge the story. That sequence reduces noise quickly.
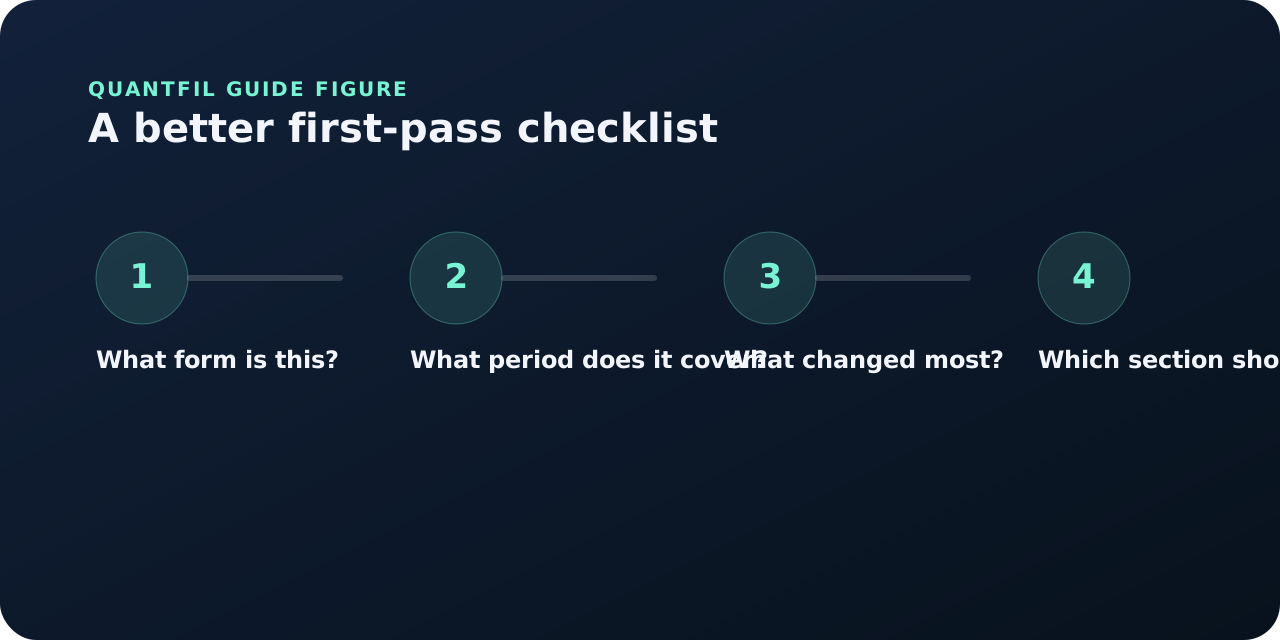
A practical workflow
The goal of a first pass is orientation. You are trying to decide what this document is for, what changed, and where the evidence will probably sit.
- Identify the form and period.
- Read the opening summary or context.
- Choose the section most likely to verify the main claim.
- Write down the first question the filing raises.
Common mistakes
The common mistake is reading too much before deciding what question the filing should answer. That makes it harder to separate useful detail from background detail.
Worked example / hypothetical, not company data
Stop a mismatch before starting analysis
Two downloaded reports share a company brand. One is the listed parent, the other a financing subsidiary; both contain debt tables.
Can their debt figures be added?
Not without understanding the consolidation boundary. The parent's consolidated figures may already include the subsidiary. First confirm legal entity, CIK, period, currency, and whether the statement is consolidated. A sophisticated ratio built on a double-counted obligation is less useful than a simple correctly scoped source note.
Source check: Use the cover page and basis-of-presentation note to identify whose financial position the table describes.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Should I always start with the statements?
Not always. Many filings make more sense once you know the form, period, and main question first.
What is the most important first check?
Knowing what document you are reading and what period it covers is usually the most important start.
Why not read every section in order?
Because the first pass is usually better when it is guided by a question rather than by the table of contents.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.