
Investors often know they should read the notes but still delay them until the end. That habit makes it easy to miss the exact detail that would have changed the whole read earlier.
- Footnotes often hold the detail that changes the quality of the filing read.
- The best note to read first is usually the one tied to the biggest tension in the filing.
- A footnote should change the next question you ask, not just add trivia.
Why this matters
This matters because the note can reveal whether the quarter's main story depended on accounting judgment, unusual customer concentration, loose contract quality, or commitments that make the balance-sheet story less comfortable.
What to look for
Look for the note most closely tied to the filing's biggest tension. That could be revenue recognition, stock compensation, debt terms, segment detail, lease obligations, or concentration language.
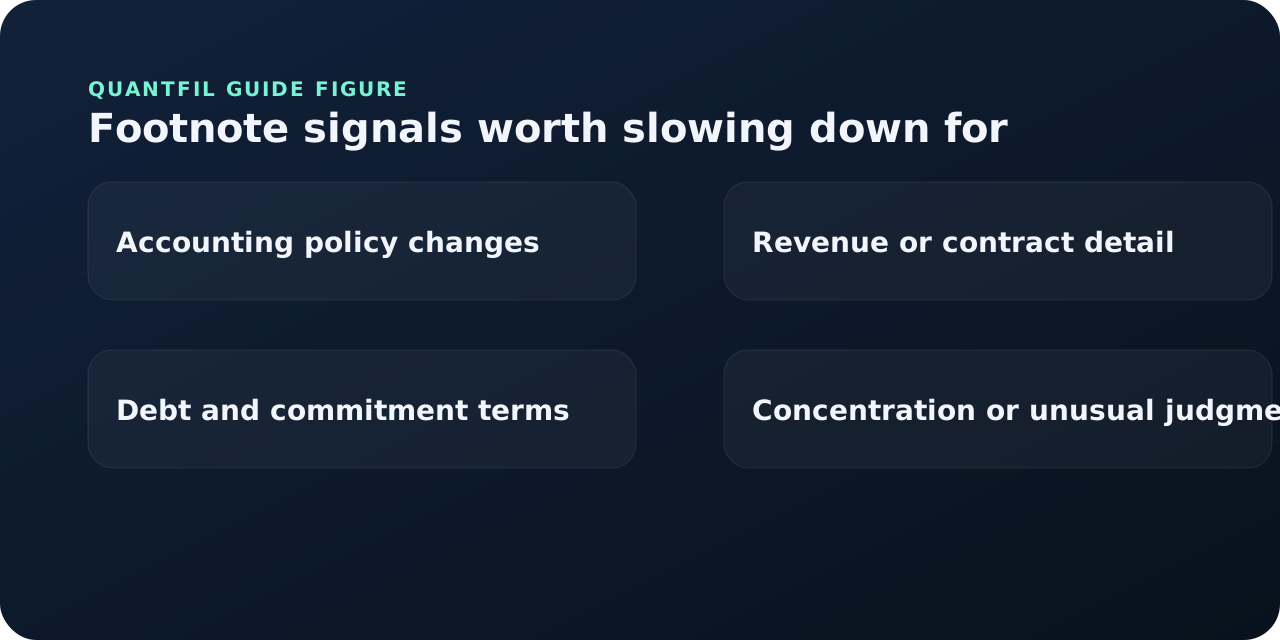
A practical workflow
Start with the filing tension, then go to the note that can either confirm the clean read or make the period look more conditional than the headline suggests.
- Identify the most important tension in the filing.
- Choose the note most likely to explain it.
- Compare the current note with the prior filing's version.
- Decide whether the footnote confirms the clean read or exposes a softer spot.
Common mistakes
The common mistake is treating footnotes like a second-pass chore. In many filings they are the only place where the business story becomes specific enough to test properly.
Worked example / hypothetical, not company data
Read the estimate behind the expense
A warranty reserve rises only slightly despite higher sales, while the note describes a change in estimated claim costs.
What would distinguish better product quality from a changed estimate?
Read the reserve roll-forward for beginning balance, provisions, claims paid, and adjustments. A smaller provision can reflect lower expected claims, but that expectation needs later evidence. Compare actual claims with earlier estimates and understand product mix. The closing reserve alone cannot explain the movement.
Source check: Carry the estimate into the next period's roll-forward and record whether actual experience supports it.
Ask yourself
- Which note would matter most if the headline story were wrong?
- Did the company become more specific, more qualified, or more silent in the note?
- What would the period look like if you trusted the footnote more than the headline?
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Try the next workflow
Frequently asked questions
Do footnotes matter for every company?
Yes, but the note that matters most changes by business model and by period.
Which note should I read first?
Usually the note tied to the quarter's biggest tension such as revenue, stock compensation, debt, or another judgment-heavy area.
Can a footnote really change the whole read?
Yes. A note can turn a clean headline into a much more conditional story.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.