
Retail investors are not wrong to start with the summary sections. They run into trouble when they stop before the notes explain what the summary left unresolved.
- Footnotes often explain the detail that the headline sections leave too smooth.
- The best note to read first is usually the one tied to the filing's biggest tension.
- A good note read often changes the question you ask next rather than just adding trivia.
Why this matters
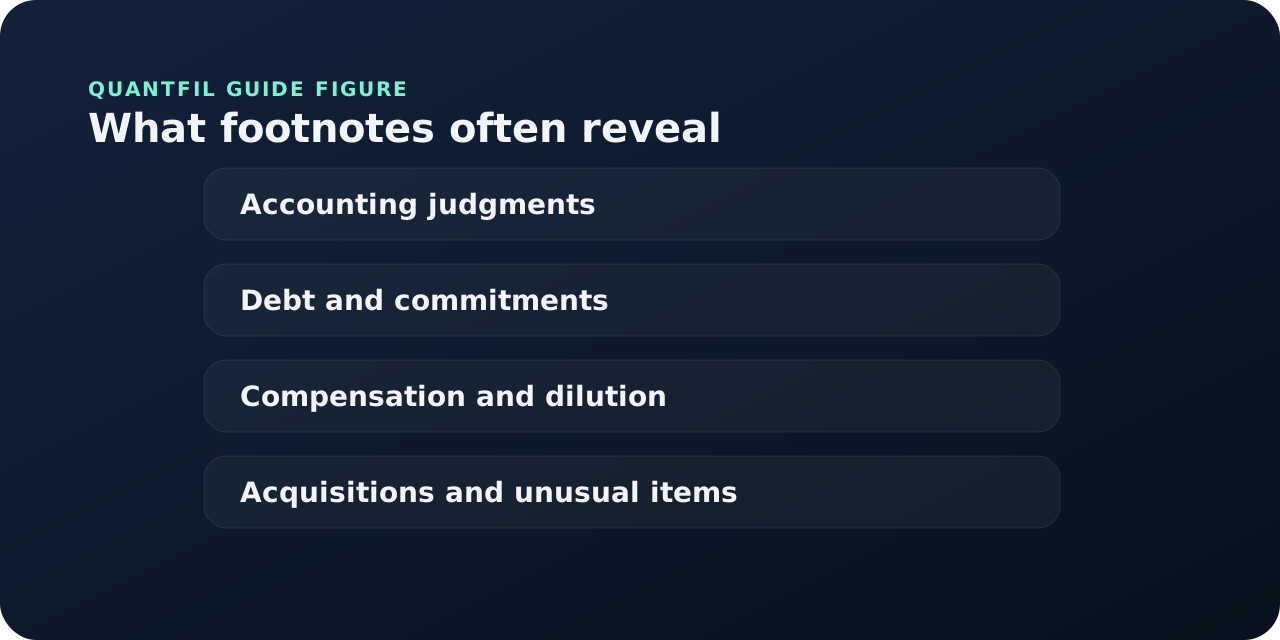
Footnotes matter because they contain debt detail, stock compensation, lease obligations, acquisition accounting, segment nuance, and accounting judgments that can materially change the business read.
What to look for
Look for the notes tied to the parts of the filing that already feel most important or least settled. If margins, dilution, debt, or one-time items look central to the story, the notes should be part of the first pass rather than the last.
A practical workflow
Use the filing summary to identify the most important tension, then go directly to the note most likely to explain it. The point is not to read every note equally. It is to find the one that makes the headline read more realistic.
- Identify the most important tension in the filing.
- Choose the note most likely to explain it.
- Read the note with the prior filing nearby.
- Decide whether the footnote changed the overall business read.
Common mistakes
The common mistake is treating the notes as a second-pass chore after the real work is done. In many filings, the notes are where the real work begins.
Worked example / hypothetical, not company data
Find the obligation absent from today's headline
A company reports strong cash generation and announces large purchase commitments payable over several years.
Should the full commitment be deducted from this year's operating cash?
No. A future commitment and a current cash payment are different measures. But ignoring the obligation also weakens the funding analysis. Read the payment schedule, cancellation terms, and nature of the commitment. Put future requirements in a separate schedule rather than silently inserting them into a historical cash-flow measure.
Source check: Distinguish disclosed commitments, recognized liabilities, and actual payments; they may overlap without being identical.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Do I need to read every footnote?
Usually no. Start with the notes that connect to the filing's most important unresolved issue.
What do retail investors miss most often?
Debt terms, stock-based compensation detail, acquisition accounting, and one-time items are common misses.
Why compare the note with the prior filing?
Because changed note language often signals the real shift more clearly than the headline sections do.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.