
Investors rarely need to become cynical about every management claim. They do need a habit for deciding which statements deserve proof and which ones sound better than they read.
- Management's framing is useful, but only once it is tested against the statements and notes.
- The prior filing is often the fastest way to catch a changed explanation.
- A claim can be directionally right and still incomplete, which is why verification matters.
Why this matters
Management claims matter because they shape how the filing is interpreted. Verification matters because a confident narrative can still sit on top of mixed margins, weak cash conversion, or a more cautious note disclosure.
What to look for
Start with the big claims around demand, margin, cash flow, liquidity, or capital allocation. Then ask which statement, note, or prior filing should confirm each one.
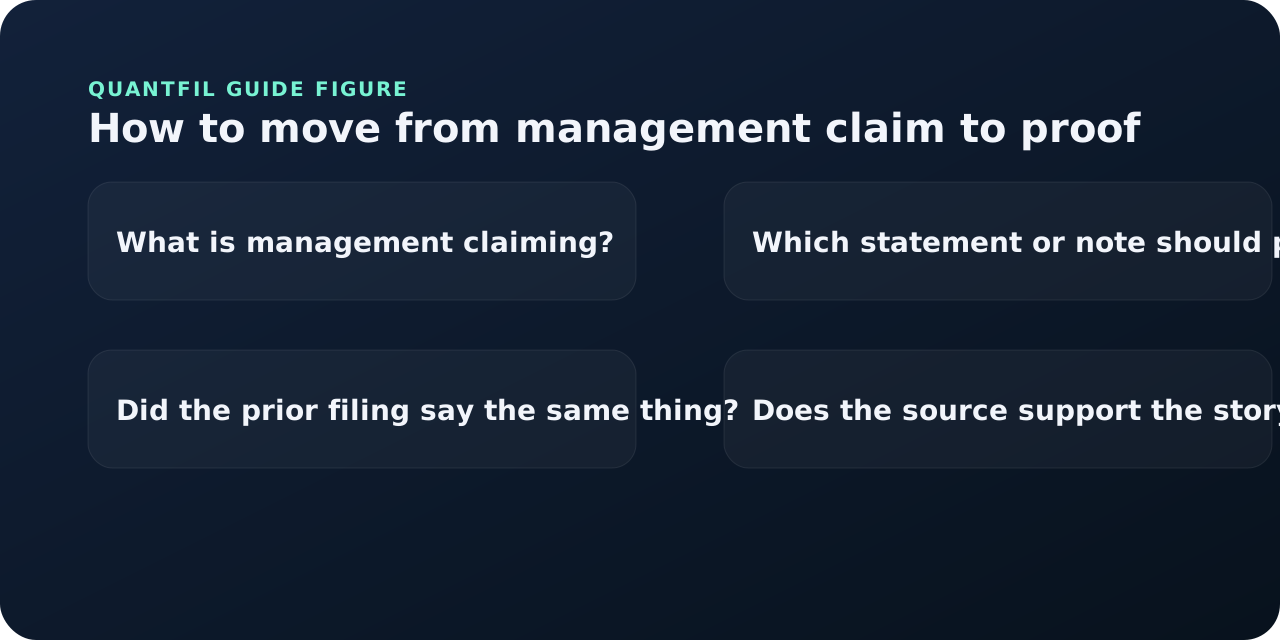
A practical workflow
Treat the filing like a proof exercise. Highlight one claim, assign it a proof section, compare it with the prior filing, and decide whether the evidence supports the explanation cleanly or only partially.
- Write down the main claim.
- Choose the statement or note that should prove it.
- Compare the claim with the prior filing.
- Decide whether the evidence is clean, mixed, or weak.
Common mistakes
The common mistake is reading management discussion as if it were already verified. The opposite mistake is ignoring it entirely. The better workflow is to take it seriously enough to test it.
Worked example / hypothetical, not company data
Test a claim that costs are under control
Management says expenses grew more slowly than revenue. Revenue increased 12%; total operating expenses increased 7%, including a lower restructuring charge.
Is the claim false because an unusual charge declined?
Not necessarily: the total comparison is arithmetically correct. The further inference that recurring operations became more efficient needs a separate test. Reconcile the restructuring change, inspect expense categories, and determine whether definitions changed. A true headline can still support a broader inference poorly.
Source check: Quote or paraphrase the claim accurately, then label your additional efficiency hypothesis as your own.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Should every management claim be doubted?
No. But the most important claims should be checked.
What kinds of claims deserve the most verification?
Claims about demand, margins, liquidity, cash generation, and capital allocation usually matter most.
Why compare with the prior filing?
Because the prior filing helps you see whether management is changing the explanation or just repeating it.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.