
The market reacts quickly to guidance, but that does not mean readers have to. A calmer process often produces a better read than the first interpretation of management tone.
- Guidance changes expectations, not facts already reported.
- Qualifiers and confidence matter as much as the number itself.
- The current filing should help you judge whether the forward-looking tone feels earned.
Why this matters
Guidance matters because it changes expectations. But the wording, confidence, and conditions around that guidance often matter more than the bare number itself.
What to look for
Look for whether management sounds more or less confident than before, how many qualifiers it uses, and whether the current filing gives the same impression as the forward-looking language.
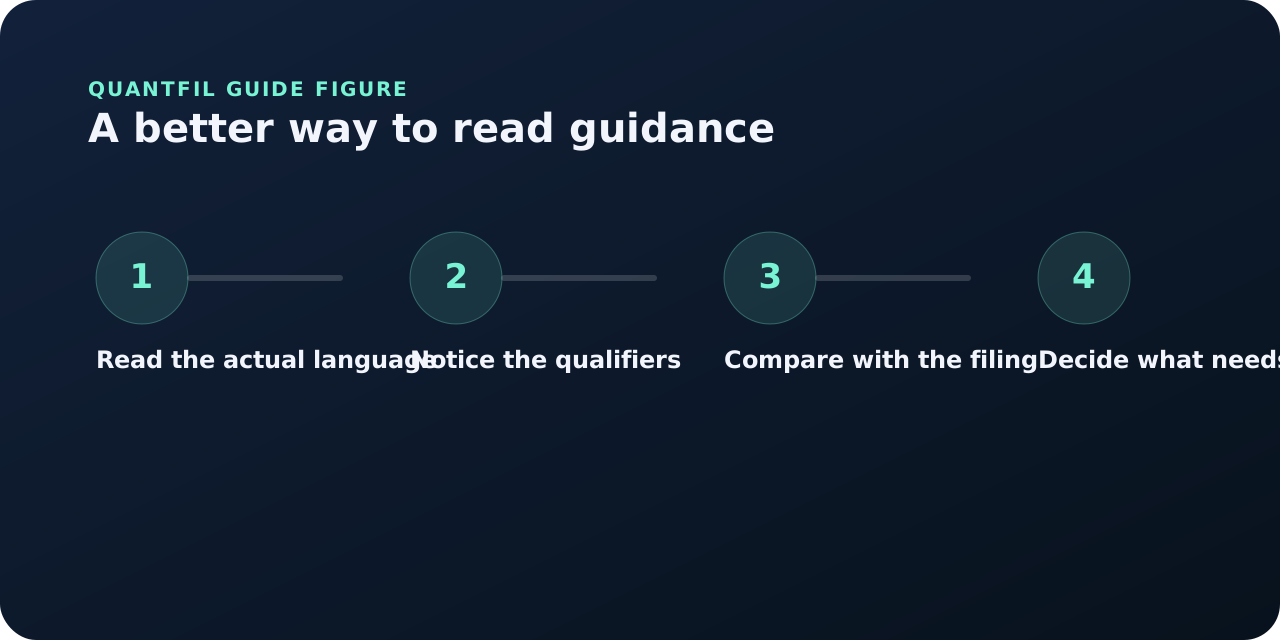
A practical workflow
Use guidance as a prompt for the next question, not as the final answer. Ask what the company is asking investors to believe about demand, margins, spend, or timing.
- Read the exact guidance language.
- Mark the conditions and caveats.
- Compare it with the current filing and prior language.
- Write down what the next report now needs to prove.
Common mistakes
The common mistake is reacting to guidance direction without reading the conditions and caveats attached to it. Another is ignoring whether the current filing supports that confidence.
Worked example / hypothetical, not company data
Keep a forecast out of the reported-results column
Management guides to next-year revenue of 1.1 to 1.2 billion after reporting 1.0 billion this year.
Has the company delivered 15% growth?
No. Fifteen percent is the growth implied by the range midpoint, not a reported result or necessarily the most likely outcome. Record the range, period, assumptions, and date. Later revisions should be compared with the earlier forecast as well as with eventual actual results.
Source check: Do not merge constant-currency or acquisition-adjusted guidance with reported revenue without reconciling the definitions.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Why not just use the guidance number?
Because the tone, conditions, and context around it can matter just as much.
Can the filing make guidance look weaker or stronger?
Yes. The current filing can make management's confidence feel more or less believable.
What is one useful habit here?
Compare the current guidance with the prior quarter's language and see what changed.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.