
Filing notebook / Tesla / FY2024
Almost flat revenue can hide a different business mix.
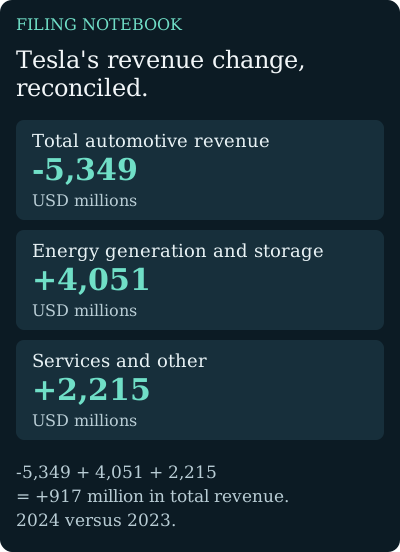
Tesla's 2024 total revenue rose by 917 million dollars. The useful story starts with the much larger changes that nearly offset each other.
Open the exact SEC 10-K1. Reconcile the headline, then take it apart
Use accession 0001628280-25-003063. Both columns cover full calendar years. Find the revenue disaggregation in Item 7 and the consolidated statements of operations; then locate the cash-flow lines in the consolidated statements of cash flows. This notebook fixes that historical source rather than replacing its numbers with the latest feed.
| Reported line | 2023 / Dec 31 | 2024 / Dec 31 | Change |
|---|---|---|---|
| Total automotive revenue | 82,419 | 77,070 | -5,349 |
| Energy generation and storage | 6,035 | 10,086 | +4,051 |
| Services and other | 8,319 | 10,534 | +2,215 |
| Total revenue | 96,773 | 97,690 | +917 |
| Operating cash flow | 13,256 | 14,923 | +1,667 |
| PPE purchases, net of sales; excluding finance leases | 8,898 | 11,339 | +2,441 |
Source: Tesla 2024 10-K, Item 7 and consolidated financial statements. PPE means property, plant and equipment.
Management's explanation: the revenue discussion connects lower automotive sales revenue to lower average selling prices and delivery mix; it connects energy growth to higher storage deployments. Read those explanations against the category totals rather than allowing either one to stand in for the whole business.
Our interpretation: “roughly flat” describes the consolidated top line, but it is a poor description of the underlying mix. Automotive declined by more than the net company change, while energy and services offset that decline. That does not make the automotive decline irrelevant. It means a whole-company conclusion needs more than one operating driver.
Keep the categories mutually exclusive. Automotive regulatory credit revenue is already inside total automotive revenue. Adding the credit line again to this bridge would overstate revenue. A detailed sales table and a consolidated bridge are different levels of the same hierarchy, not extra sources of sales.
2. A stronger cash engine did not produce a larger residual
Operating cash increased by 1,667 million. The reported PPE purchases line increased by 2,441 million. A deliberately narrow subtraction gives:
2023: 13,256 − 8,898 = 4,358 million.
2024: 14,923 − 11,339 = 3,584 million.
Change: 3,584 − 4,358 = −774 million.
The business generated more operating cash, but that increase did not cover the increase in this particular spending line. Both statements can be true. It is a useful check on the habit of treating higher operating cash as automatically meaning more cash available after investment.
Label the subtraction as operating cash less this PPE line. It is not a universal definition of free cash flow. The PPE line excludes finance leases; the statement also reports solar energy system purchases separately. Other cash demands are not captured by the subtraction. Before comparing this residual with another issuer's measure, reconcile the definitions. Meta's notebook demonstrates why lease principal can change the answer.
A smaller residual does not establish that investment was wasteful. A larger one would not establish that investment was sufficient. The calculation addresses funding in that year. The return on spending requires a separate operating question and later evidence.
3. Turn the bridge into a verification sequence
- Start with category revenue, not a stock narrative. Reconcile the categories to total revenue. Keep nested items such as regulatory credits inside their parent category.
- Read costs beside the growth. Find the costs and gross-margin discussion. Higher revenue in one category does not establish the same profit contribution as an equal amount in another.
- Identify price, volume, and mix separately. Management's explanation may discuss all three. Do not manufacture a precise contribution for a driver the filing does not quantify.
- Compare cash and spending over matching years. Record the exact PPE definition and inspect leases and separate investment lines before naming a cash-flow measure.
- Choose what to monitor next. Track category revenue and gross profit, storage deployments, automotive pricing and mix, and the cash-to-spending bridge. Keep a reported change separate from a forecast about it.
On a first pass, skip unrelated historical commentary, not the footnote needed to define your measure. If the question is whether energy growth changes the earnings mix, reading consolidated revenue alone will never finish the job.
4. Try to invalidate the easy conclusion
“Energy growth fixed the automotive decline.” What is missing from that claim?
The bridge concerns revenue, not equivalent margins, returns on capital, or future cash flows. You would need category costs and operating evidence to support a profit claim. It is also possible for one category to offset another in a single year without establishing a durable trend. The defensible statement is simply that growth in energy and services more than offset the automotive revenue decline in this year's consolidated sales total.
Can we use the 3,584 million residual as a buyback budget?
No. Debt service, lease obligations, other investments, liquidity needs, and financing decisions still matter. A defined subtraction is not an allocation decision. Open the worksheet, record what you included, and inspect the obligations before discussing what is available.
Continue the investigation
Read business mix · Avoid cash-flow traps · Verify management's explanation.
Use the current Tesla or General Motors reference to start a separate dated study. Do not combine their current data with this fixed annual comparison.
Use and provenance
The table transcribes the linked SEC filing; the bridges are Quantfil's calculations. Interpretations are educational, not investment advice or claims of professional assurance. No conclusion about valuation follows from these two bridges. Report a correction with the source location.