
These sections are often skipped because they can sound dry. But they are some of the clearest places where a filing can reveal a change in the company's operating or reporting risk.
- Legal and controls sections can change how much confidence a filing deserves.
- New specificity or changed wording often matters more than boilerplate language.
- These sections are especially useful when compared with the prior filing.
Why this matters
They matter because litigation, regulatory issues, or control weaknesses can change how much confidence the reader should place in management's framing and the stability of the business.
What to look for
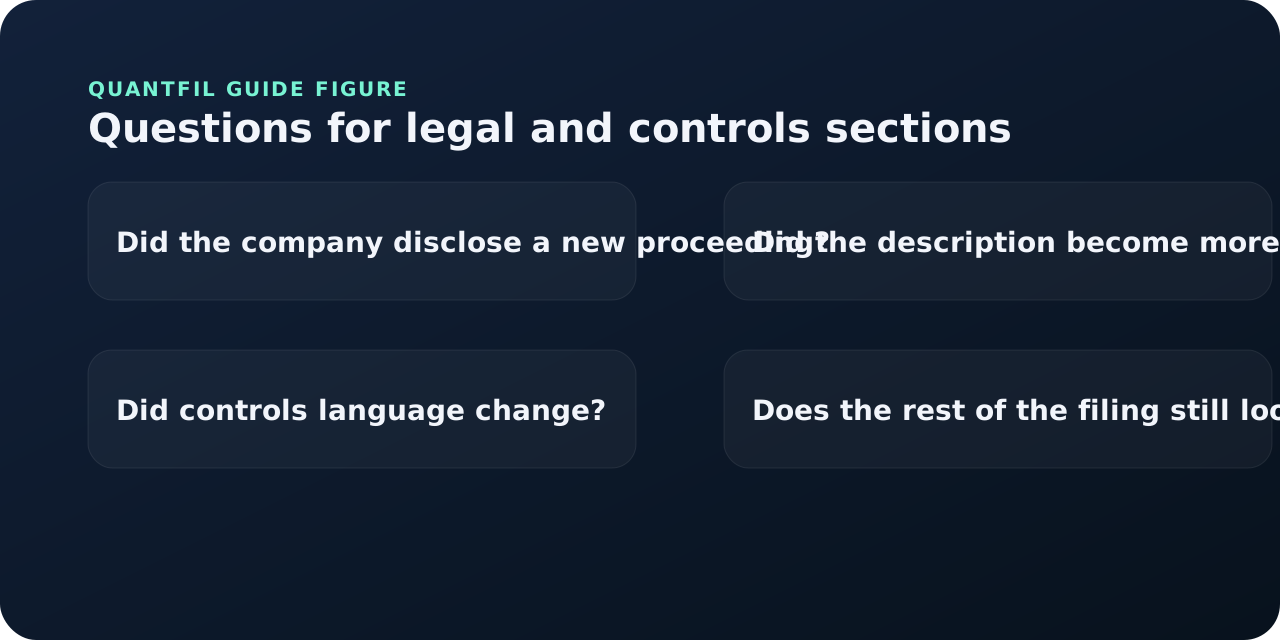
Look for new proceedings, more detailed language, changes in internal-control discussion, or any sign that the company is becoming more defensive about its reporting environment.
A practical workflow
Use these sections as a confidence check. They may not change the core business model, but they can change how firmly the rest of the filing should be trusted.
- Scan the current legal and controls sections.
- Compare the language with the prior filing.
- Ask whether the confidence level of the rest of the filing changed.
- Decide whether the issue deserves deeper source work.
Common mistakes
The common mistake is assuming the sections do not matter because they are not operating metrics. They can matter precisely because they affect the reliability and risk around those metrics.
Worked example / hypothetical, not company data
A control weakness is not a quantified loss
A filing reports a material weakness in controls over revenue accounting, but does not announce a restatement.
Can you conclude either that the statements are wrong or that the weakness is harmless?
Neither follows automatically. Read the affected process, management's assessment, remediation steps, and any auditor discussion or later amendment. A material weakness is important information about control reliability. It does not supply an amount by which a statement should be adjusted.
Source check: Track remediation evidence in later filings rather than treating a plan to fix the issue as proof it has been fixed.
Choose a company source
These reference pages link to dated filings. Apply the question to the document, rather than treating the reference data as an analyst opinion.
Frequently asked questions
Do these sections matter for most investors?
Yes, because they can change the confidence level of the whole report.
Should I compare them with the prior filing?
Usually yes. That is often how the important change becomes visible.
Does a controls issue automatically break the thesis?
Not automatically, but it should raise the level of care in the next read.
Primary sources and further reading
Use and provenance
Educational analysis, not investment advice. The worked exercise is hypothetical, not a company disclosure. Use the primary sources above for definitions and the exact filing for company-specific facts. Publishing and accountability · Report a correction.